
Hundreds of thousands of USD can secure a new citizenship. But the travel rights attached to that citizenship are not an unchanging commitment. When entry policies change, investors need to reassess what they actually hold.
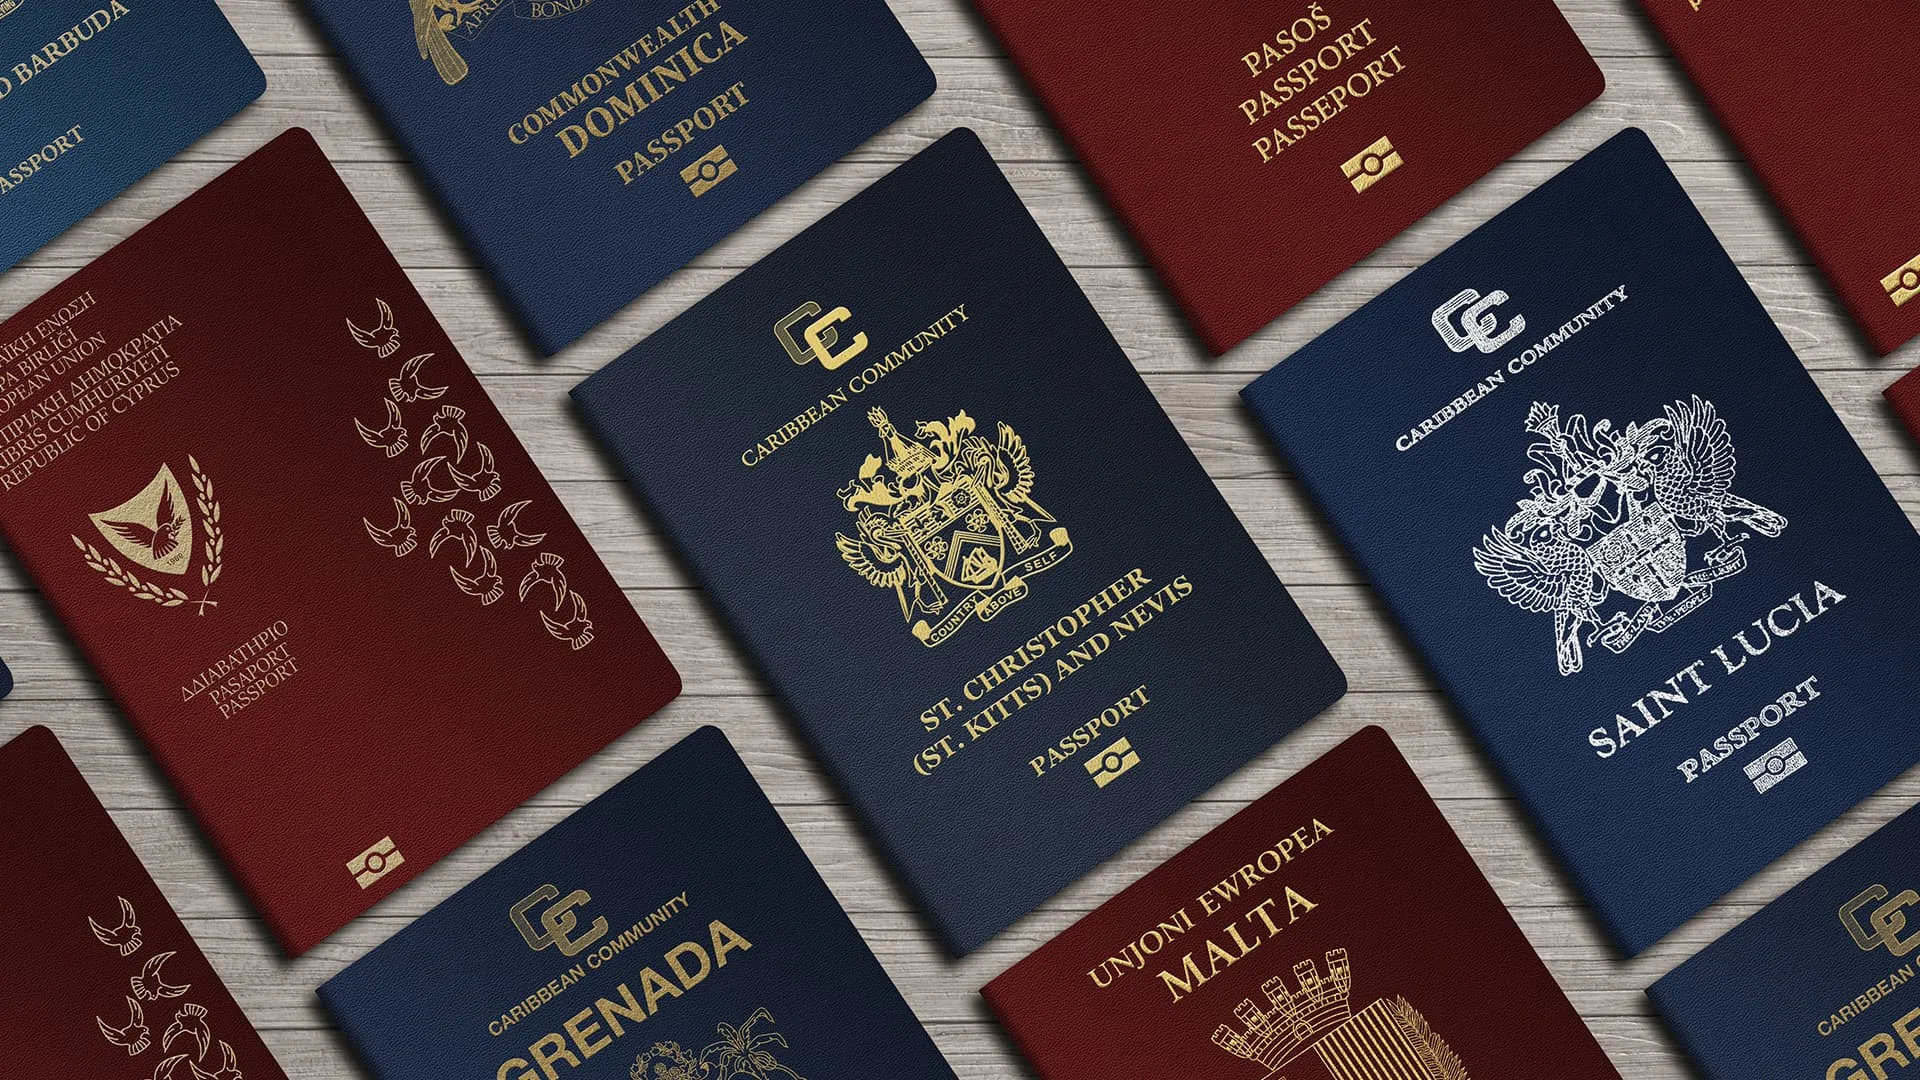
In citizenship by investment, one of the most common questions is: “How many countries does this passport provide visa-free access to?”
It is an understandable question. International mobility is one of the important benefits that lead families to consider acquiring a second citizenship.
But for a decision costing hundreds of thousands of USD, the number of visa-free countries should perhaps not be the starting point, much less the endpoint, of the assessment.
There is a fundamental difference between two things often discussed together: citizenship is a legal status, while visa-free access is a policy determined by the receiving country.
A family may lawfully acquire citizenship and retain it, while the travel benefits that originally led them to choose the programme change.
This is no longer a hypothetical risk.
1. When a passport’s value changes even though its holder has done nothing wrong
In 7/2023, the United Kingdom introduced visa requirements for citizens of Dominica and Vanuatu, citing concerns related to the two countries’ citizenship-by-investment programmes.
That decision highlights an important reality: visa-free access is not entirely within the control of the passport-issuing country, much less within the investor’s control.
By 12/2025, the European Commission continued to identify citizenship-by-investment programmes in the Eastern Caribbean as a security concern, while emphasising the possibility of using the visa-waiver suspension mechanism under the new rules.
This does not mean that every Caribbean passport will lose visa-free access to the Schengen Area. But it makes policy risk a variable that needs to be taken seriously.
For investors, the lesson is not that second-citizenship programmes have lost their value.
The lesson is that a benefit subject to change should not be valued as though it were guaranteed forever.
2. A passport should not be assessed as a ranking
Suppose two countries both offer citizenship-by-investment programmes.
Country A offers visa-free access to more destinations. Country B offers fewer destinations, but is better aligned with the investor’s business plans, family needs or long-term strategy.
If only the number of visa-free countries is compared, A may look more attractive.
But if the family frequently travels between Vietnam, the UAE, the United States and Europe, what they need to analyse is access to those specific markets, actual entry conditions and policy stability.
A passport that provides access to many countries the family rarely visits does not necessarily create more value than a citizenship that meets their specific needs.
In addition, visa-free access for short visits does not confer the right to reside, work or conduct business in the destination country.
The number of destinations is therefore an easily promoted metric, but it is not enough to measure strategic value.
3. In what way is a second citizenship like insurance?
Entrepreneurs do not buy insurance because they want a loss to occur.
They pay premiums to mitigate the consequences of adverse situations.
A second citizenship can be viewed through a similar lens, although it is not an insurance product in the legal sense.
A family with an established business and a stable life in Vietnam may have no plans to move abroad in the next ten years. Nevertheless, they want to retain an additional option for their place of residence, travel rights or the future of the next generation.
The value of that option is not necessarily reflected in the number of flights taken each year.
It lies in the family’s ability to have another course of action when circumstances change.
But the comparison with insurance also has limits.
An insurance contract can clearly define the scope of coverage, compensation amounts and exclusions. A citizenship, by contrast, does not guarantee that every other country will continue to grant its holder the same entry rights as today.
Investors therefore need to distinguish between two types of value:
Legal value: citizenship status and the rights recognised by the laws of the country granting citizenship, subject to specific conditions.
International utility value: the ability to travel, reside or access other markets, which depends on multiple external legal systems and policies.
The first and second types do not necessarily change together.
4. How much does a 250.000 USD investment really cost?
Consider a hypothetical family of four weighing a citizenship-by-investment programme with a total cost of approximately 250.000 USD.
This figure is for illustration only, not a quotation for any specific programme.
If the family expects to use the benefits over 20 years, the initial cost equates to 12.500 USD per year on a simple allocation basis, before accounting for the time value of money, opportunity costs and additional expenses.
But that calculation rests on a major assumption: the benefits the family values will remain valuable throughout those 20 years.
If, after the fifth year, an important destination changes its visa policy, the passport’s practical value may decline significantly for this family, while having little impact on another.
The same programme, at the same cost, can produce entirely different investment outcomes.
It is also important to distinguish a non-refundable contribution from an investment in real estate that may be transferable. An asset-backed investment does not mean that capital recovery is guaranteed. Liquidity, the holding period, the resale price and transaction costs can all affect the final outcome.
For example, Dominica’s programme currently lists two investment routes starting at 200.000 USD: a contribution to the Economic Diversification Fund or an investment in approved real estate. The two options have different financial mechanisms and risks, even though their initial minimum investment amounts are equivalent.
The question, therefore, should not simply be “Which programme is the cheapest?”
It is:
“Which benefits is the family paying for, for how long, and what happens if those benefits change?”
5. Second citizenship cannot replace a residence and asset strategy
Another misconception is to view second citizenship as a comprehensive solution to every international need.
In practice, a family may need several different tools.
If the goal is to live in Dubai over the long term, UAE residence rights may be more directly relevant to that plan.
If the goal is to run a business in the United States, an appropriate corporate structure and immigration status may matter more than the number of countries the passport allows its holder to visit visa-free.
If the goal is asset protection, the central issues may lie in ownership structures, risk management, succession and tax obligations.
Second citizenship can complement these strategies. But it does not automatically replace them.
Indeed, a new citizenship may create additional obligations or issues requiring due diligence, such as rules on multiple citizenship, dependants’ rights, civic obligations and other legal implications.
A good strategy is not the one with the most products.
It is the one that addresses the most important needs with a reasonable level of complexity.
6. So when is a second passport truly worthwhile?
There is no single wealth threshold that determines whether a family should invest in second citizenship.
A family with 20 million USD in assets may not need another citizenship if its existing residence arrangements and travel rights already fully meet its needs.
Conversely, a family with more modest assets but frequent international travel needs may consider the additional options highly important.
The difference lies in objectives, financial capacity, benefits that can be used in practice and risk tolerance.
Before investing, the family should test an assumption:
If, five years from now, this passport no longer offers visa-free access to one of our most important markets, would we still want to hold that citizenship?
If the answer is yes, because the family has other long-term reasons, the investment may have a stronger strategic foundation.
If the answer is no, the decision depends substantially on a benefit beyond the investor’s control.
And that is a risk that needs to be recognised before signing a contract.
A second passport can be a strategic family asset. But its greatest value does not lie in the number of countries printed in a ranking.
It lies in the genuinely useful choices that citizenship offers — even when the world does not unfold as originally anticipated.
EMMAI GLOBAL
International Analysis & Strategy
From Vietnam to Global
This article is for reference only and does not constitute legal advice. Regulations may change.
Family
I want to prepare the best for my children. But that does not mean they have to choose it.
Global families
How many countries does a global family need?
Global families
Obtaining a residence card is only the first step: How can you maintain immigration rights for the whole family?
Global families
How do a family’s taxes change after obtaining a green card or residence abroad?